


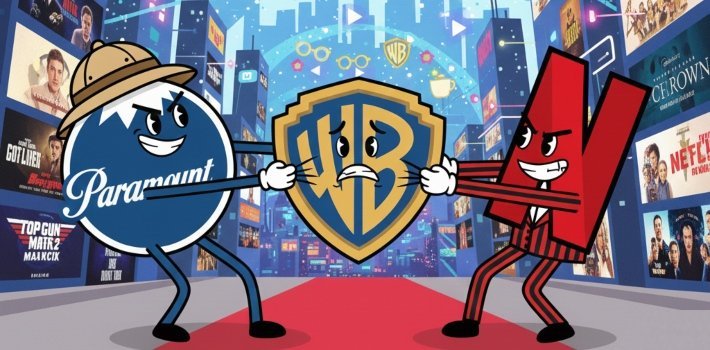
After Warner Bros. Discovery Board of Directors released its recommendation against Paramount’s $30.00 per share all-cash tender offer, both companies, Paramount and Netflix have responded with different perspectives of the situation, as they have claimed in different statements.


Paramount has affirmed its commitment to acquiring Warner Bros. Discovery, urging WBD shareholders to send a clear message to WBD. It also reiterates its commitment to pursuing all options to deliver the value and benefits of its offer for all stakeholders.
On the other hand, Netflix welcomes the recommendation from the Warner Bros. Discovery Board of Directors for stockholders to reject the “unsolicited offer” from Paramount Skydance Corporation, launched on December 8, 2025.
Paramount
Paramount’s offer provides WBD shareholders superior value compared to the transaction with Netflix, including the certainty of 100% cash and no exposure to equity market fluctuations:
- Paramount’s offer is $30 per share in cash versus Netflix’s cash component of only $23.25 per share (an $18 billion difference in the aggregate);
- The value of Netflix’s offer has been further reduced as its share price trades below the bottom of the “collar” on its stock component;
- Netflix’s offer would leave WBD shareholders owning a highly leveraged stub in Global Networks and WBD’s Board provides no valuation of that stub; and
- Netflix’s offer has a dollar-for-dollar reduction to what WBD shareholders will receive tied to the net debt on Global Networks.
Paramount affirms that is “highly confident” offer would receive timely regulatory approval because “it would enhance competition in the creative industries rather than entrench a dominant streaming monopoly that the Netflix transaction envisions”.
Paramount adds that it has lined up all necessary financing to deliver its offer to WBD shareholders, and it is not subject to any financing conditions. Paramount’s offer will be financed by $41 billion of new equity backstopped by the Ellison family and RedBird Capital and $54 billion of debt commitments from Bank of America, Citi and Apollo.
David Ellison, Chairman & CEO, Paramount explains: “We remain committed to bringing together two iconic Hollywood studios to create a unique global entertainment leader. Our proposal clearly offers WBD shareholders superior value and certainty, a clear path to close, and does not leave them with a heavily indebted sub-scale linear business. I have been encouraged by the feedback we have received from WBD shareholders who clearly understand the benefits of our offer. We will continue to move forward to deliver this transaction, which is in the best interest of WBD shareholders, consumers, and the creative industries”.
Paramount notes that:
- WBD’s own narrative of the actions that led to its inferior transaction with Netflix reveals a process which was not run to secure the best offer for WBD shareholders.
- WBD seeks to justify racing to conclude an inferior deal with Netflix with a “kitchen sink” litany of purported questions and concerns.
- WBD seeks to mislead its shareholders into believing this is a complicated question about legal documents.
- Paramount’s December 4 offer included an equity commitment from the Ellison family trust, which contains over $250 billion of assets (more than 6x the equity funding commitment) including approximately 1.16 billion Oracle shares and tens of billions of dollars in other assets.
- WBD shareholders deserve to know this information and understand what is being hidden from them.
- The Board of WBD failed to even make the determination that Paramount’s $30 per share all-cash offer “could reasonably be expected to lead to a superior proposal” under WBD’s transaction agreement with Netflix. This failure is yet another example of WBD’s pattern of ignoring Paramount’s value-maximizing offer.
- Paramount has acted to provide WBD shareholders with transparency and a voice by taking its superior offer directly to them.
“Yet from mid-September all the way through to December 4, what is glaring is the absolute resistance on the part of WBD to even engage in a single negotiating session with Paramount or its advisors, and a refusal even to provide a mark-up of any transaction document”, adds the company.
Netflix
“The Warner Bros. Discovery Board reinforced that Netflix’s merger agreement is superior and that our acquisition is in the best interest of stockholders”, affirms Ted Sarandos, Netflix co-CEO. “This was a competitive process that delivered the best outcome for consumers, creators, stockholders and the broader entertainment industry. Netflix and Warner Bros. complement each other, and we’re excited to combine our strengths with their theatrical film division, world-class television studio, and the iconic HBO brand, which will continue to focus on prestige television. We’re also fully committed to releasing Warner Bros. films in theaters, with a traditional window, so audiences everywhere can enjoy them on the big screen”.
Netflix co-CEO Greg Peters concludes: “By acquiring Warner Bros., we’ll be able to offer audiences and creators around the world even more choice, value and opportunity. This transaction is fundamentally pro-consumer, pro-innovation, pro-creator and pro-growth. Together we will deliver an even broader selection of great series and films that audiences can watch at home and in theaters, while driving long-term value for our stockholders. We’re excited to begin this new chapter and continue to entertain and delight fans around the world”.
Additionally, the company has sent a letter to WBD stockholders to “reiterate why we believe the agreed-upon transaction with Netflix is the right deal, with the right partner, at the right time – and to set the record straight on some key points”.
The text confirms that Netflix transaction is better on multiple fronts, such as: superior financing certainty and clear funding structure, confidence in regulatory approvals, and fully negotiated agreement designed for execution.
Additionally, it explains that its transaction is superior, “with a total equity value per share for WBD stockholders of $27.75 (comprised of $23.25 per share in cash and $4.50 per share in Netflix stock with a collar mechanism to protect stockholders as we move toward closing), plus the additional value of the shares of Discovery Global that WBD stockholders will receive pursuant to the separation of Discovery Global”.
To conclude, it remarks the reasons why its merge should be selected due to the company’s background, experience and influence in the entretainment industry.


Comments are closed